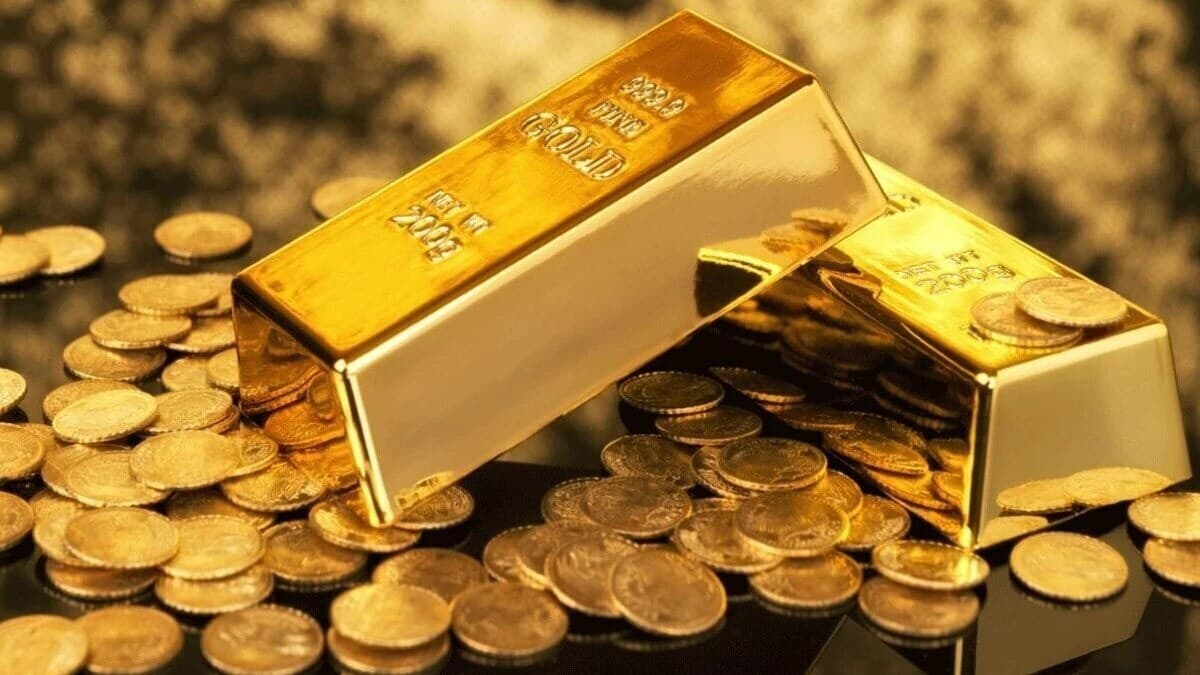
Indian households have shared an enduring cultural and financial relationship with gold for centuries. From weddings and festive buying during Dhanteras to emergency household collateral, gold has always served as the premier store of family wealth. However, with domestic 24-karat gold prices scaling successive all-time highs, investors face a critical dilemma:
- Is the current gold rally underpinned by structural macroeconomic fundamentals?
- Or has gold reached a cyclical top that leaves late entrants vulnerable to a sharp price correction?
Understanding the primary drivers behind this rally helps clarify whether fresh allocation makes sense today.
1. Macro Drivers Behind the Record Gold Rally
Gold prices do not rise in isolation. The metal’s upward trajectory reflects three powerful global macroeconomic forces:
A. Record Central Bank Accumulation
Central banks worldwide—led by the Reserve Bank of India (RBI), the People’s Bank of China (PBOC), and monetary authorities across emerging markets—have been accumulating physical bullion at record pace. This de-dollarisation drive is designed to diversify sovereign reserves away from US Treasuries and mitigate vulnerability to sanctions. When central banks buy dozens of tonnes per quarter, structural demand removes significant supply from liquid markets.
B. Geopolitical Fragmentation and Safe-Haven Demand
Prolonged regional conflicts, maritime shipping disruptions in the Red Sea, and escalating tariff tensions have kept the geopolitical risk premium elevated. During periods of heightened global uncertainty, institutional capital reliably rotates out of riskier paper assets into gold as the definitive counter-party-free safe haven.
C. Central Bank Monetary Policy & Interest Rate Cycles
Gold yields zero nominal income—it pays no interest or dividends. Consequently, when central banks maintain elevated interest rates, cash and fixed deposits become relatively more attractive. Conversely, when major central banks begin cutting benchmark policy rates, bond yields decline, real yields compress, and non-yielding bullion becomes significantly more competitive.
2. Physical Gold vs. Digital Alternatives: A Critical Assessment
For wealth accumulation, buying physical jewellery is among the least cost-effective vehicles available. Jewellery carries steep retail markups and friction costs that destroy real compounding returns.
| Investment Vehicle | Making / Management Fee | Purity Risk | Liquidity & Ease of Sale | Capital Gains Tax Treatment |
|---|---|---|---|---|
| Physical Jewellery | 10% – 25% (unrecoverable) | High (requires hallmarking checks) | Low (haircut on resale) | Standard physical asset taxation |
| Gold Coins / Bars | 3% – 8% minting premium | Moderate (storage concerns) | Moderate (must sell to jeweller) | Standard capital gains |
| Gold ETFs / Mutual Funds | 0.20% – 0.50% expense ratio | Nil (99.5% pure physical backing) | High (instant exchange execution) | Taxed at applicable slab / debt rules |
| Sovereign Gold Bonds (SGB) | Nil (issued at market price) | Nil (sovereign government backing) | Secondary market exchange traded | Tax-exempt on holding to maturity |
For investors seeking price exposure rather than wearable ornamentation, Gold ETFs and Sovereign Gold Bonds (purchased in the secondary market) eliminate melting charges, purity fraud, and bank locker expenses entirely.
3. Investment Strategy: Lump Sum vs. Phased Staggering
Deploying a massive lump sum into any asset trading at its historical zenith involves substantial draw-down risk. If global tensions ease or central banks pause easing cycles, gold prices routinely witness healthy 5% to 8% technical retracements.
Recommended Allocation Rules:
- The 10%–15% Portfolio Anchor: Gold should not represent your primary wealth generator—equities hold that mandate over multi-decade horizons. Rather, bullion serves as a portfolio insurance policy against currency debasement and systemic market shocks. Keep gold allocation bounded between 10% and 15% of your total liquid net worth.
- Systematic Accumulation (SIP): If you plan to allocate fresh capital to gold, split your intended deployment into 6 equal monthly tranches via a Gold ETF or Gold Mutual Fund. This dollar-cost averages your purchase price and insulates you from local price peaks.
Summary
Gold has maintained purchasing power across thousands of years of monetary history. While trying to time the exact short-term pinnacle is speculative, maintaining a disciplined, low-cost digital gold allocation provides an essential counterbalance to equity volatility in every balanced Indian investment portfolio.