Between 2020 and late 2021, India's startup ecosystem experienced an unprecedented liquidity wave. A new venture "unicorn" (a privately held company valued at $1 billion or higher) was being minted nearly every week. Global venture capital firms poured billions of dollars into high-friction consumer tech, subsidizing ride-hailing fares, food delivery, and quick commerce. In that era of ultra-low global interest rates, gross merchandise value (GMV) and customer acquisition velocity were treated as the sole proxies for business viability.
Then arrived the sharp macroeconomic tightening of 2022–2024. As the US Federal Reserve and the Reserve Bank of India raised policy rates, the cost of global capital surged. Global VCs retreated, valuations experienced steep write-downs, and cash-burn runways dried up overnight, forcing painful corporate restructurings and layoffs.
Yet, this prolonged "funding winter" proved to be a vital institutional crucible. Today, Indian technology companies have emerged far more resilient, fiscally disciplined, and structurally oriented toward sustainable profitability and public domestic capital markets.
1. The Death of Cash Burn: Prioritizing Unit Economics
The operational mantra across startup boardrooms has executed a complete 180-degree shift:
$$\text{From: Growth at All Costs} \longrightarrow \text{To: Contribution Margin Positive & Operating Cash Flows}$$
- Discontinuation of Destructive Subsidies: The days of 50% discount coupons funded by offshore venture checks have disappeared. Consumer platforms across mobility, food delivery, and e-commerce now levy platform fees, handling charges, and delivery surcharges, systematically moving contribution margins into positive territory.
- Rationalization of Fixed Overheads: Tech companies streamlined redundant workforce layers, renegotiated vendor contracts, and reduced customer acquisition costs (CAC) by focusing on organic repeat user retention rather than aggressive blitzscaling.
- Demonstrated Public Market Success: The turnaround trajectories of listed companies like Zomato and PB Fintech proved to the broader market that consumer internet business models in India can generate robust, recurring free cash flows at maturity.
2. The Dalal Street Transformation: Domestic Capital Dominance
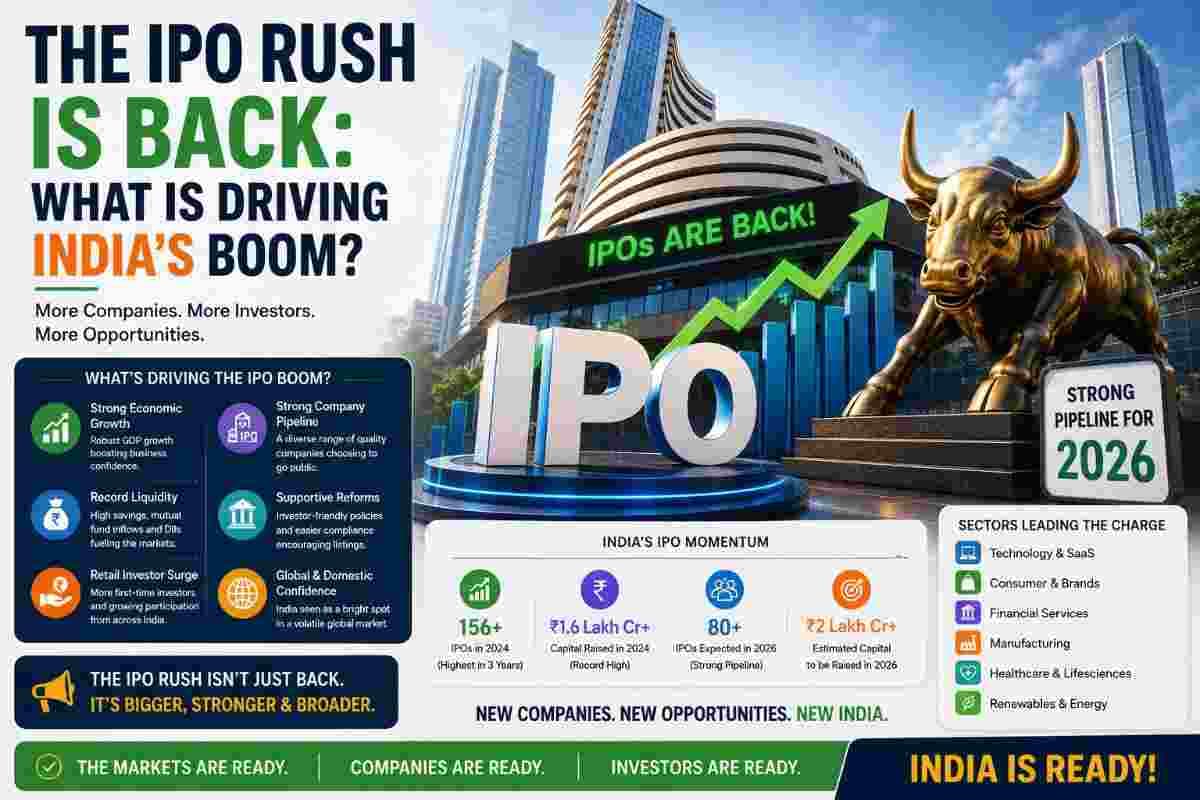
Historically, Indian founders harbored ambitions of listing on New York's Nasdaq or the NYSE, believing domestic public markets lacked the appetite for tech multiples. Today, Dalal Street (NSE and BSE) has become the premier listing destination for several reasons:
| Parameter | 2020–2021 VC Bubble Era | Modern IPO Landscape |
|---|---|---|
| Primary Valuation Metric | GMV growth, monthly active users | EBITDA margins, PAT, free cash flow conversion |
| Capital Source | US & East Asian late-stage crossover funds | Domestic Institutional Investors (DIIs) & retail SIP flows |
| Listing Preference | Offshore ADR/GDR listings | National Stock Exchange (NSE) & BSE mainboard / SME |
| Governance Standards | Founder-centric board control | Rigorous SEBI disclosure norms & independent oversight |
Domestic Indian mutual funds, fueled by consistent monthly retail SIP flows exceeding ₹20,000 crore, provide deep, resilient domestic liquidity. Furthermore, an Indian listing builds immediate brand credibility and customer trust that offshore listings cannot match.
3. Sectoral Rotation: DeepTech, B2B, and Manufacturing
While consumer-facing mobile apps captured the first generation of venture capital, institutional investment has pivoted toward foundational engineering and supply-chain capabilities:
- Aerospace and DeepTech: Startups in orbital launch vehicles, private satellite constellations, and drone technologies are securing sovereign and commercial defense contracts.
- Agritech and Cold-Chain Logistics: Companies bridging the intermediary gap between farmers and end processors are unlocking operational efficiencies across perishable produce supply chains.
- Fintech 2.0 & WealthTech: Moving beyond basic UPI payments, innovative platforms are democratizing insurance penetration, corporate credit lines, and structured investment products for non-metro Tier-2 and Tier-3 demographics.
4. Guiding Principles for the Modern Enterprise Founder
For entrepreneurs building in the current macroeconomic climate, the operational playbooks have permanently reset:
- Monetization Architecture from Day One: If a product requires artificial pricing subsidies to demonstrate consumer demand, the business model is fundamentally flawed. Clear paths to gross margin profitability must be established early.
- Conservative Cash Runway Management: Maintaining a minimum 24-month liquid runway protects operations against unexpected macro disruptions and removes the pressure of raising capital from distressed positions.
- Institutional-Grade Governance: Transparent audited financials, strict related-party transaction controls, and robust internal audit systems must be prioritized years ahead of any intended draft red herring prospectus (DRHP) filing.
Summary
The funding winter was not a setback for Indian innovation; it was a necessary cleansing of structural excesses. By replacing vanity growth metrics with genuine operating discipline, Indian founders are building world-class, financially self-sustaining institutions built to endure public market scrutiny.